
2026 Financial Success Roadmap: The Ultimate Guide to Wealth (GIR)
Master the 2026 Financial Success Roadmap with our strategic 50/30/20 rule, investment tips and a 12-month checklist. Start building your wealth today with GIR.
Welcome to January 1, 2026. The global economy has moved past the volatile inflationary shocks of the early 2020s into a new era of AI-driven productivity and asymmetric opportunities. However, with automation reshaping job security and the cost of living remaining high in cities like London, New York, Berlin, and Paris, the "old" rules of thumb no longer suffice.
This roadmap is not a generic list of tips; it is a 365-day strategic blueprint. Whether you are a Gen Z professional in Berlin or a mid-career manager in Chicago, this guide provides the mathematical rigor and psychological empathy required to achieve "Financial Sovereignty"—the state where your money works for you, rather than you working for your money.
Part 1: The Theoretical Framework (The "Why" Behind the Wealth)
Before we touch the spreadsheets, we must understand the "laws of the jungle." Modern wealth management is built on three cornerstone theories that remain valid in 2026:
1. The 50/30/20 Rule (Modernized)
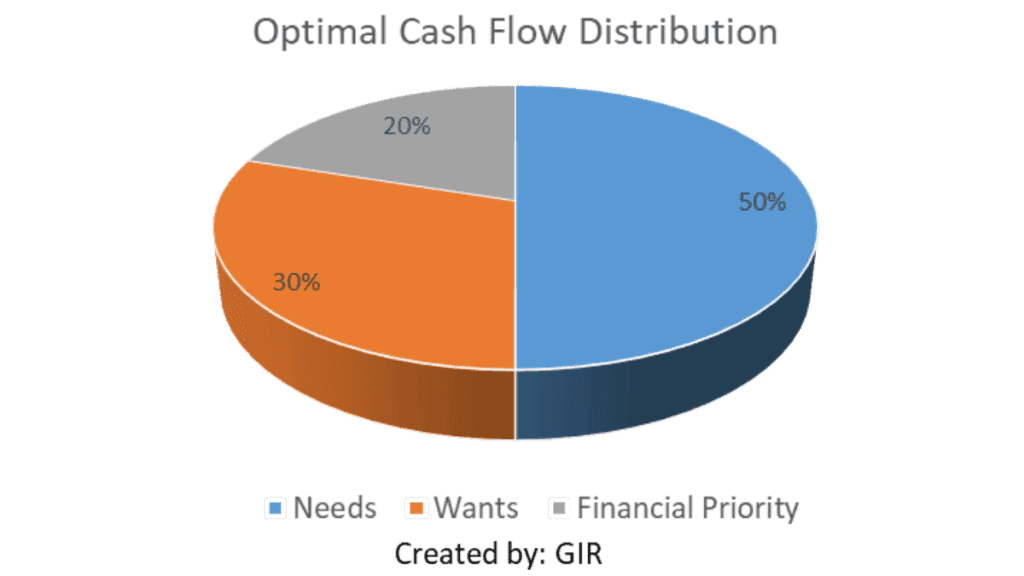
Popularized by Senator Elizabeth Warren, this rule is your baseline. However, in 2026, with the "subscription economy" and high housing costs, we refine it:
- 50% Needs: Rent/Mortgage, Utilities, Food, Insurance.
- 30% Wants: Travel, AI-enhanced entertainment, dining.
- 20% Financial Priority: Debt repayment and wealth building.
2. The 4% Rule & Sequence of Returns Risk
The 4% rule is a historical retirement-planning rule of thumb, not a guarantee that a portfolio will last 30 years. Sustainability depends on asset allocation, fees, inflation, taxes, withdrawal flexibility, market sequence and retirement length. Test several scenarios rather than treating one rate as universally safe.
3. The Psychology of Money
As Morgan Housel famously noted, "Doing well with money isn’t necessarily about what you know. It’s about how you behave." In 2026, the biggest threat to your wealth isn't the stock market—it's lifestyle inflation and the urge to chase "hype" assets.
Phase 1: The Foundation (January – March)
"The Financial Hygiene Quarter"
January: The Great Audit & The "Subscription Creep"
Subscription spending varies widely by household and country; review your own bank and card statements rather than relying on an unsourced average number of digital services.
- The Net Worth GPS: Calculate your Net Worth.$$\text{Net Worth} = \text{Total Assets (Cash + Investments + Real Estate)} - \text{Total Liabilities (Debt)}$$
- Audit of Subscriptions: If a tool doesn't save you time or bring you joy, cancel it.
- Defining the "North Star": Use Value-Based Spending. If you value "Freedom," your savings rate is your most important KPI.
February: The 2026 Debt Decimation Strategy
With interest rates stabilizing but remaining higher than the 2010s, debt is a weight you cannot afford.
- The Avalanche Method: Mathematically superior. Pay off the highest interest rate first.
- The Snowball Method: Psychologically superior. Pay off the smallest balance first for a "dopamine hit."
- Emergency Fund 2.0: In the age of AI-induced job shifts, 3 months of savings is risky. Aim for 6–9 months in a High-Yield Savings Account (HYSA).
March: Tax Engineering (USA & EU Focus)
- USA: If eligible, consider an HSA (Health Savings Account). It is often described as triple-tax-advantaged because eligible contributions, investment growth and qualified medical withdrawals can receive favourable tax treatment; eligibility and qualified-expense rules apply.
- UK/Europe: Maximize your ISA (UK) or PEA (France). Utilize the "Allowance" before the fiscal year ends.
- Legal Protection: Update your Digital Will. In 2026, your crypto keys, social media, and digital IP are assets that need a legal successor.
Phase 2: The Optimization (April – June)
"Maximizing Human and Financial Capital"
April: The 2026 Portfolio Construction
We are moving away from "stock picking" toward evidence-based investing.
- Illustrative portfolio framework: A global stock fund and a global bond fund are common building blocks, but allocation should match time horizon and risk tolerance. Bitcoin and gold are volatile and are not guaranteed hedges; any alternative-asset allocation is optional and should not be treated as a universal 5% rule.
- Rebalancing: If your AI-tech stocks have surged, sell the winners and buy the laggards to maintain your risk profile.
May: Skill Arbitrage (Human Capital Theory)
Economist Gary Becker argued that "Human Capital" is your most valuable asset.
- The AI Pivot: Use May to learn practical AI tools relevant to your work. Productivity gains vary by task, skill, employer and tool; do not assume a universal “10x” improvement or a measured pay gap without a dated study.
- Income Diversification: Aim for "The Rule of Three"—One salary, one dividend/interest stream, and one "passion project" income stream.
June: Lifestyle Design & The Mid-Year Review
- Conscious Spending: "Frugality, quite simply, is an intentionality about spending," says Joshua Fields Millburn.
- Mid-Year KPI Check: Is your Savings Rate above 20%? If not, adjust your "Wants" category.
Phase 3: The Growth (July – September)
"Aggressive Wealth Acceleration"
July: Real Estate & Physical Assets
- The "Hybrid Work" Opportunity: Properties in "Tier 2" cities with high-speed internet are the new goldmines in 2026.
- REITs: For those who hate being landlords, Real Estate Investment Trusts provide liquid exposure to the housing market.
August: Tax-Loss Harvesting & Automation
- The Pro Move: If you have losing positions, sell them to offset capital gains. This is Tax-Loss Harvesting.
- The "set and forget" System: Ensure your DRIP (Dividend Reinvestment Plan) is active. Compound interest is the "eighth wonder of the world" (as often attributed to Einstein).
September: The FIRE Calculation
- The "FI" Number: Take your annual expenses and multiply by 25.$$\text{Target FI Number} = \text{Annual Expenses} \times 25$$
- Where do you stand? Even if you don't want to retire, knowing your number gives you "F-You Money"—the power to walk away from a toxic job.
Phase 4: The Legacy (October – December)
"Protection, Philanthropy, and Planning"
October: Risk Mitigation & Cyber-Security
- Insurance Audit: In 2026, medical costs are higher. Ensure your "Out-of-Pocket" maximum won't bankrupt you.
- Cyber-Financial Hygiene: Use hardware keys (like YubiKey) for your bank accounts. Your identity is your credit.
November: The Generosity Framework
- Strategic Giving: Use a Donor-Advised Fund (USA) to get an immediate tax deduction while distributing the money over time.
- Family Transparency: Hold a "Money Talk." Tell your family where the important documents are. Silence on money creates chaos for heirs.
December: The 2027 Launchpad
- Bonus planning: One possible approach is to direct most of a bonus toward high-interest debt, savings or long-term goals while reserving some for enjoyment. A 70/30 split is only an example, not a universal financial rule.
- Reflection: What was your "Return on Life" (ROL)? Did your money buy you more time with people you love?
Illustrative Case Studies: 2026 Profiles (hypothetical examples)
Case Study A: The "Emerging Professional" (Berlin, Germany)
- Profile: Clara, 26, Junior AI Consultant.
- Income: €50,000 / year (Net ~€2,600/month).
- Strategy: * Housing: €900 (Room in a shared flat).
- The "Public Pension" Hedge: Clara does not assume the state pension will cover all retirement expenses; she assesses expected benefits against her own projected spending. She invests €600/month into a World MSCI ETF via a low-cost neo-broker.
- Skill Growth: Spends €100/month on certifications to reach the €75k bracket by 2028.
Case Study B: The "Squeezed Middle" (Austin, USA)
- Profile: Marcus & Sarah, 38, Two kids.
- Income: $140,000 / year (Household).
- Strategy:
- Tax Strategy: Maxing out the HSA (up to $8,750 for 2026 family HDHP coverage (self-only coverage: $4,400; eligibility and prorating rules apply). Source: IRS Revenue Procedure 2025-19) to use as a "super IRA."
- Education: Contributing $400/month to a 529 Plan to hedge against future college costs.
- Debt: Refinanced their 2023 high-interest mortgage in early 2026 as rates dipped.
Case Study C: The "Digital Nomad / Freelancer" (Global/Portugal)
- Profile: David, 32, UI Designer.
- Income: $90,000 (Variable).
- Strategy:
- The "Buffer" Rule: Keeps a 12-month emergency fund because income is volatile.
- Tax Residency: Uses a "NIF" in Portugal but ensures he isn't double-taxed by the US (FEIE).
- Investment: Focuses on "High Yield" dividend stocks to provide a base income during slow freelance months.
The 2026 Mastery Tracking Template
| Month | Financial KPI | Task | Target Metric |
| Jan | Net Worth | Financial Audit | Assets > Liabilities |
| Feb | Debt Ratio | The Avalanche Paydown | Debt-to-Income < 30% |
| Mar | Tax Efficiency | Max Out 401k / ISA | 100% Contribution |
| Apr | Diversification | Portfolio Rebalance | +/- 5% of Target |
| May | Human Capital | New High-Income Skill | 1 Certification |
| Jun | Savings Rate | Mid-Year Audit | > 20% Net Income |
| Jul | Real Estate | REIT or Property Analysis | Research 3 Assets |
| Aug | Tax Loss | Harvest Portfolio Losers | Offset Gains |
| Sep | FI/RE Number | Calculate "Days of Freedom" | Increase by 30 days |
| Oct | Security | Update Passwords & Wills | 100% Secure |
| Nov | Philanthropy | Charitable Contribution | 1–5% of Income |
| Dec | Bonus Flow | The 70/30 Distribution | 70% Invested |
Conclusion: The Behavioral Edge
Wealth in 2026 is not about a "lucky crypto play" or a "meme stock." It is about the systematization of discipline. By following this roadmap, you move from the "Reactive Class" (those who worry about bills) to the "Proactive Class" (those who design their destiny).
References & Research:
- The Psychology of Money by Morgan Housel.
- The 4% Rule - William Bengen (Journal of Financial Planning).
- Human Capital Theory - Gary Becker (University of Chicago).
- The Simple Path to Wealth - JL Collins.
Review checklist
- Distinguish essential costs, discretionary spending, debt interest, emergency reserves and long-term goals.
- Treat rules of thumb as starting points; adapt them to the reader’s obligations, risk capacity and local tax or benefit rules.
- Use dated official guidance for any tax limits or regulated product terms, and avoid presenting a generic plan as individual financial advice.
Practical checks for the user or business
A practical financial plan starts from the household’s current cash flow, expensive debt, emergency needs and time-bound goals. Set milestones that can be reviewed against actual progress, and make room for uncertainty rather than presenting a single forecast as a guaranteed path to wealth.
Related Resources
Personal Finance
High-Yield Savings Accounts: 2026 Strategy Guide
Discover optimal high yield savings accounts 2026 strategies, FDIC-insured yield techniques, and expert insights for maximizing cash returns.
Company & Business
Inside Corporate Culture: What Really Drives Company Success
What corporate culture really is, what research says about its effect on results, and how to judge a company's culture as a job seeker or investor.
Latin America & Caribbean
Invest in Brazil: The Definitive Strategic Roadmap for Institutional Investors
Looking to invest in Brazil? Discover our institutional-grade roadmap covering top growth sectors, stock market access, and real estate opportunities. Start!
The information provided is for educational and informational purposes only and does not constitute financial, investment, tax, or legal advice.